


Tax season problems rarely begin when a return is filed. They begin months earlier, when receipts are missing, bank accounts are mixed, payroll records have not been reconciled, or a business owner cannot explain a large deposit. Knowing how to prepare for tax season means building an organized financial record before deadlines create pressure.
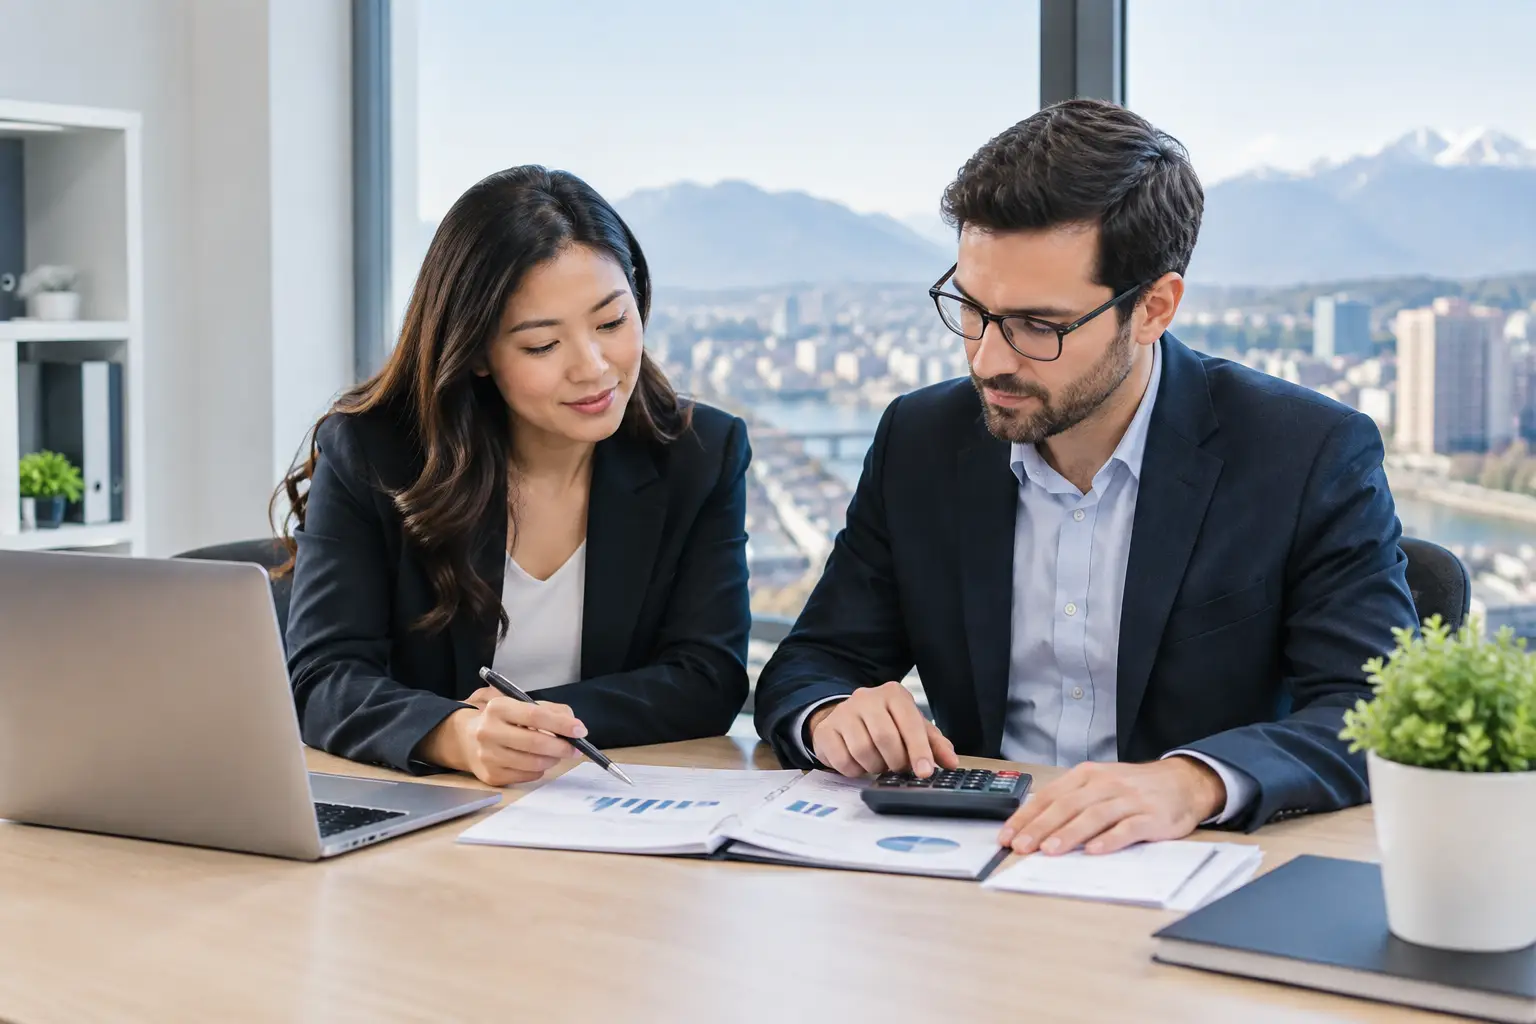
For Canadian individuals, self-employed professionals, and incorporated businesses, preparation is not just an administrative exercise. It affects deductions, cash flow, filing accuracy, and the ability to respond if the Canada Revenue Agency requests support for amounts reported on a return. A practical process also gives your accountant time to identify issues before they become expensive corrections.
How to Prepare for Tax Season: Start With Complete Records
Begin by creating one secure location for tax documents. This may be a cloud folder, accounting software file repository, or a clearly labeled paper system. The format matters less than completeness and consistency. Do not wait until a T1 personal return, T2 corporate return, GST/HST filing, or payroll slip is due before gathering documents.
Individuals should collect income slips and supporting documents for employment income, investment income, rental income, pension income, benefits, and foreign income. Keep records of deductible expenses, charitable donations, medical expenses, tuition amounts, child care expenses, moving costs where eligible, and RRSP contributions. If you sold investments or real estate, retain purchase records, sale statements, legal documents, and improvement invoices that may affect the adjusted cost base or taxable gain.
Business owners need a broader package. Gather business bank and credit card statements, invoices issued, supplier bills, receipts, loan statements, equipment purchases, vehicle records, payroll reports, prior-year tax returns, and correspondence from the CRA. If your bookkeeping is behind, bring it current before tax preparation starts. A stack of receipts is evidence, but it is not a usable set of books.
Separate Personal and Business Activity
One of the most common causes of inaccurate returns is commingling personal and business transactions. A dedicated business bank account and business credit card make it easier to identify revenue and deductible expenses. They also make bookkeeping faster and reduce the risk of missing income or claiming personal costs as business expenses.
This is especially relevant for contractors, real estate investors, consultants, medical professionals, lawyers, trucking operators, and startup founders. A personal payment used for a legitimate business cost can still be recorded, but it needs a clear explanation and supporting receipt. Regularly reviewing transactions is easier than reconstructing their purpose ten months later.
Reconcile Books Before Reviewing Deductions
Tax planning should be based on accurate numbers, not assumptions. Reconcile bank accounts, credit cards, loans, payroll liabilities, and sales records. Compare accounting income to deposits received and investigate differences. A deposit may be a customer payment, loan proceeds, a shareholder contribution, a transfer between accounts, or a refund. Each category has different tax treatment.
For companies, review accounts receivable and accounts payable as well. Unpaid invoices, customer deposits, prepaid expenses, and accrued costs can affect the timing of reported income and expenses. A corporation using an accrual basis cannot simply rely on cash moving through its bank account.
If your records show an unexpected profit or loss, do not assume the result is wrong. Review it. Higher income may reflect improved sales, unrecorded prior-period work, or a missing expense account. A loss may be legitimate, but it may also signal invoices that were never entered, duplicate expenses, or owner withdrawals recorded incorrectly.
Review Expenses With Documentation in Mind
A cost must be incurred to earn income to be deductible, and reasonable documentation remains essential. The question is not only whether an expense sounds business-related. You should be able to show what was purchased, when it was purchased, who provided it, how much it cost, and why it supported income-producing activity.
Pay particular attention to expenses that commonly require allocation or detailed records. Home office costs depend on workspace use and eligibility. Vehicle expenses require mileage support and a business-use calculation. Meals and entertainment are often limited. Capital assets such as vehicles, machinery, computers, and certain equipment may need to be depreciated rather than deducted immediately.
For rental properties, keep income statements, mortgage interest records, property tax bills, insurance invoices, repair costs, and invoices for capital improvements. Replacing a broken item may be a current repair, while an expense that substantially improves or extends the life of the property may receive different treatment. The distinction depends on the facts.
Plan for Filing Deadlines and Cash Requirements
A filed return and a paid tax balance are not always due on the same date. Individuals generally must file by April 30, while self-employed individuals and their spouses generally have a later filing deadline. However, any balance owing is generally due by April 30. Filing later does not eliminate interest on an unpaid balance.
Corporate deadlines also require planning. A corporation generally files its T2 return within six months after its fiscal year-end, while the payment deadline for taxes owing may be earlier depending on the corporation’s circumstances. GST/HST filing and payment dates vary by filing frequency. Payroll remittances follow their own schedule and should not be treated as money available for operating expenses.
Set aside funds for expected taxes as income is earned. This matters most for self-employed taxpayers, landlords, commission-based earners, and businesses with variable margins. If a tax bill will strain cash flow, address it before the deadline. A payment arrangement may be possible in some cases, but it does not remove the need to file accurately and on time.
Complete Payroll, GST/HST, and Information Returns
Tax season is not limited to income tax returns. Employers must ensure payroll records agree with wages paid, source deductions remitted, and benefits provided. T4 slips and summaries need to be prepared accurately and issued on time. Incorrect payroll reporting can create employee confusion, CRA follow-up, penalties, and avoidable amendments.
Businesses registered for GST/HST should reconcile sales tax collected with sales tax paid on eligible inputs. Confirm that tax was charged where required, that input tax credits are supported, and that exempt, zero-rated, and taxable revenue have been classified correctly. A bookkeeping system that records tax consistently throughout the year makes this review far more reliable.
If you paid contractors, interest, dividends, or certain other amounts, assess whether information returns are required. This is an area where the answer depends on the payment type, recipient, and business structure. Do not assume every payment is treated like payroll, or that no reporting is needed because the recipient is an independent contractor.
Address Changes and Complex Transactions Early
Some tax matters require more than a year-end checklist. Tell your tax professional early if you incorporated, sold a business, bought or sold a property, began renting out a home, received foreign income, held foreign property, moved provinces, became a non-resident, or performed work in the United States. These events can change filing obligations and may require records that are difficult to recreate later.
The same applies to cryptocurrency transactions, shareholder loans, intercompany transfers, estate matters, and major equipment purchases. A transaction may be commercially sensible while still creating a tax reporting obligation. Early review gives you options; a review after the transaction is complete is often limited to reporting the result.
Make Tax Preparation a Monthly Process
The most effective tax season checklist is completed throughout the year. Reconcile accounts each month, save receipts as they are received, review outstanding invoices, and track mileage and home office use in real time. Schedule a quarterly review of income, expenses, sales tax, payroll, and projected tax owing.
For growing businesses, consider whether internal bookkeeping is sufficient. A construction company managing job costs, a physician operating through a professional corporation, or a real estate investor with several properties will need more detailed records than a simple service business. The right accounting process depends on transaction volume, industry requirements, entity structure, and the decisions you need to make from the numbers.
BOMCAS Canada supports personal taxpayers, self-employed professionals, corporations, and specialized businesses with tax preparation, bookkeeping, payroll, GST/HST, and cross-border tax services. Bringing organized records to the process allows the work to focus on accurate filing and appropriate tax treatment rather than emergency cleanup.
Start with the month you are in. Reconcile one account, collect one category of missing documents, and identify one issue that needs professional review. Those small actions are what turn tax season from a deadline crisis into a controlled financial process.


 View Our Location
 181 Meadowview Bay, Sherwood Park, AB T8H 1P7, Canada (Online Clients Only)